October is designated as National Retirement Security Month, a nationwide effort to raise awareness about the importance of saving for retirement and a reminder that’s it’s never too early (or too late) to save. This month is a great time to review your retirement savings strategy to make sure you’re on track to meet your retirement goals. It’s also the perfect time to consider enrolling in the SURS Deferred Compensation Plan (DCP).
Saving for Your Future
All SURS-covered members have access to the SURS Deferred Compensation Plan (DCP). The DCP is a voluntary savings plan that complements your other SURS retirement Plan and allows you to save additional money toward your retirement. Your core SURS retirement plan provides valuable benefits and may be your primary source of income in retirement. However, you are likely to need additional retirement savings to maintain your current lifestyle after you retire. The DCP is designed to help you build those additional savings and to supplement the benefits you’ll receive from your core SURS retirement plan.
Give Your Retirement Savings Time to Charge
No matter how old you are (25 to 45 or older) or how far you might be from retirement, right now is the best time to start building additional retirement savings through the DCP. The sooner you start, the more time you give your savings to grow (or charge) and to take advantage of compound growth when the money you earn on your contributions also earns money.
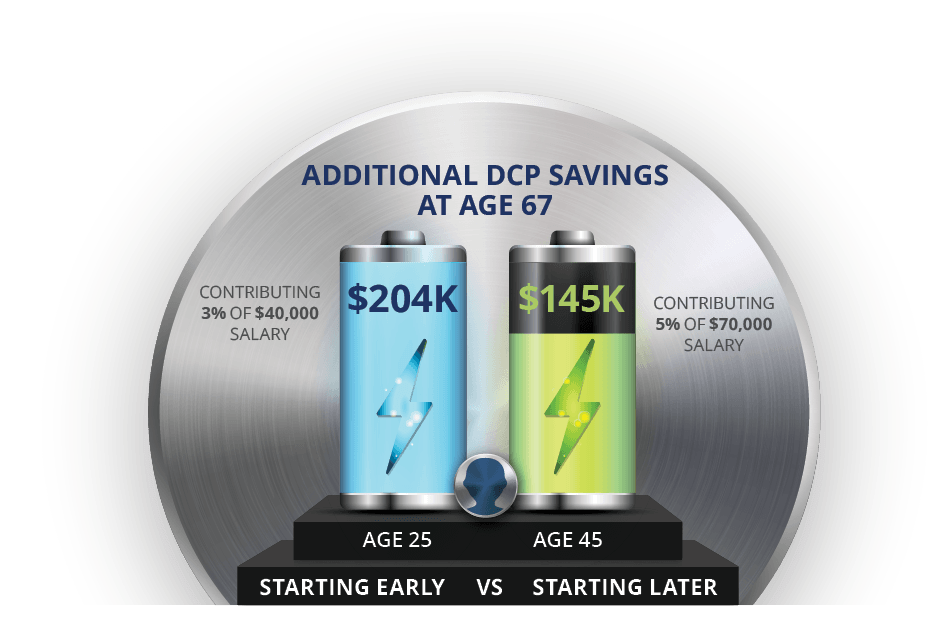
The illustration of batteries shows the potential impact of waiting to save through the DCP. The fuller blue battery on the left reflects the potentially larger balance achieved by starting to save early at age 25, contributing 3% of a $40,000 salary up to age 67. The smaller charge on the green battery on the right shows the potentially smaller balance achieved by waiting to save until age 45, contributing 5% of a $70,000 salary up to age 67. Missing the benefits of compound growth between ages 25-45 could mean significantly less at retirement, even if your salary is higher at age 45.
You have Access to the SURS Deferred Compensation Plan (DCP)
Click in the link below to enroll and charge your retirement.
Still have questions?
Speak to a Representative
Call the SURS Defined Contribution Contact Center, weekdays, 7 a.m. to 7 p.m., CT at 800-613-9543.
Meet with a Counselor
Learn About the DCP
Register to attend an upcoming DCP informational webinar and review additional DCP resources at surs.org/dcp.
This message is provided to you for informational purposes only and does not serve, either directly or indirectly, as legal, financial or tax advice. You should always consult a qualified, professional legal, financial, and/or tax advisor when making decisions related to your individual situation. Enrolling in and contributing to the SURS Deferred Compensation Plan (DCP) is optional. Eligible SURS members may enroll in and contribute to the DCP at your own election, and you may change your enrollment election and/or your contribution amount at any time.
Eligible members who elect to enroll in and contribute to the DCP are responsible for selecting an investment strategy from the investment options made available through the DCP based on your own investing goals. Members who do not select their investment strategy will have any contributions invested in the DCP’s default investment option, the SURS Lifetime Income Strategy (LIS). You should carefully consider the investment objectives, risks, performance, and expenses of the investment options offered through the DCP before investing. There is no guarantee that any investment option will achieve its stated objective and there is no guarantee against loss.
Plan administrative services are provided by Voya Institutional Plan Services, LLC (VIPS). VIPS is a member of the Voya® family of companies and is not affiliated with State Universities Retirement System of Illinois (SURS).
*SURS Defined Contribution Account Representative are registered representatives of Voya Financial Advisors, Inc., member SIPC. Information from the registered representatives is for educational purposes only and is not legal, tax or investment advice. Neither SURS nor Voya Financial is authorized to give you investment advice. You should obtain a financial advisor to receive investment recommendations regarding your specific situation.